

Tax compliance and small and medium-sized enterprises: Is the legislator out of touch with reality?
What you can expect from this article
Last week, I spoke to tax adviser Torsten Stockem, a partner at the law firm Energiesozietät, about Section 38 of the EGAO. The Act has been in place for several years and deals with the trialling of alternative audit methods. During our conversation, Torsten and I realised that there are many fascinating aspects surrounding the Act and the section in question. As well as discussing the substance of the matter, we raised the following question during our discussion: How can small and medium-sized enterprises meet the requirements set by the legislator?
Why Section 38 of the EGAO is a potential flashpoint for small and medium-sized enterprises
The provision often referred to as „§ 38 EGAO“ relates to Article 97 § 38 of the Introductory Act to the Tax Code and concerns the testing of alternative audit methods. During our programme, Torsten Stockem particularly emphasised that, for the first time, the legislator is providing something akin to a definition of a tax risk control system. The text of the Act states as follows:
A control system comprises all internal measures designed to ensure that
1. the tax bases are accurately recorded and taken into account, and
2. the taxes due on this are paid in full and on time.
The sentence that follows immediately afterwards is particularly intriguing:
The tax control system must continuously identify tax risks.
For with this sentence, the legislator makes it clear that simply drawing up a plan does not mean the job is done. Instead, companies must continuously review their processes. Are new risks emerging? Have existing risks been eliminated? Have legal requirements changed? Does a control measure still function in the same way as before following a system change?
Large corporations employ a TCMS team – but what about small and medium-sized enterprises?
Even setting up a dynamic Tax Compliance Management System (TCMS) requires a well-thought-out, structured approach. However, the ongoing monitoring and adaptation of the TCMS demands far greater resources. Large corporations often have their own tax department, ideally including a tax compliance team. However, the reality is usually quite different for small and medium-sized enterprises (SMEs). Whilst full-time tax compliance managers can still be found in larger SMEs, the situation is quite different, particularly in smaller companies. In many businesses, tax compliance is handled by individual staff members alongside their other duties. How realistic is it to „continuously map tax risks“ in such a setting?
The diplomatic answer is: there is no single, universally applicable solution for all small and medium-sized enterprises. The role may therefore be based within the tax department, the finance department or within a higher-level compliance structure. What is crucial is that the person in charge possesses tax expertise and sufficient experience. After all, the task is not solved by a job title, but by well-prepared processes, up-to-date specialist knowledge and taking the right action. If SMEs are unable to muster the necessary resources, tax advisers and auditors are useful points of contact. However, Torsten Stockem emphasises that, in such cases, the external specialists must be very closely integrated into the day-to-day processes. A brief annual review of the documents is not sufficient.
How medium-sized businesses achieve tax compliance
There’s no point in complaining. Nor is it the case that the legislator wants to harass us small and medium-sized enterprises out of boredom. Tax certainty and risk management are important to me as an entrepreneur and to my staff, too. After all, taken together, these two factors mean long-term resilience – in other words, a matter of survival. As the managing director of a small or medium-sized enterprise, I have several options for tackling the issue of „ongoing compliance“:
- If our company can afford it, a: Full-time Tax Compliance Manager on the subject.
- In addition, I have the opportunity to join a Finance specialist to assign the task as an additional area of responsibility. In doing so, business processes will be revised to such an extent that, through the use of AI and automation, as well as input from all departments, the overall workload will be reduced and shared amongst several people.
- As a third option, I can provide a external expert bring in. Ideally, the law firm my company already works with will be able to provide me with a specialist in tax compliance. I will involve this person closely in my processes.
 A triple premiere at the IDW Annual Congress 2021
With more than 200 participants attending in person, plus over 100 more online, the IDW Annual Congress last Thursday and Friday was a hive of activity. In a first, this year’s congress was not held in Baden-Baden, but in the federal city of Bonn. In another first, hsp joined the ranks of the 20 exhibitors for the first time.
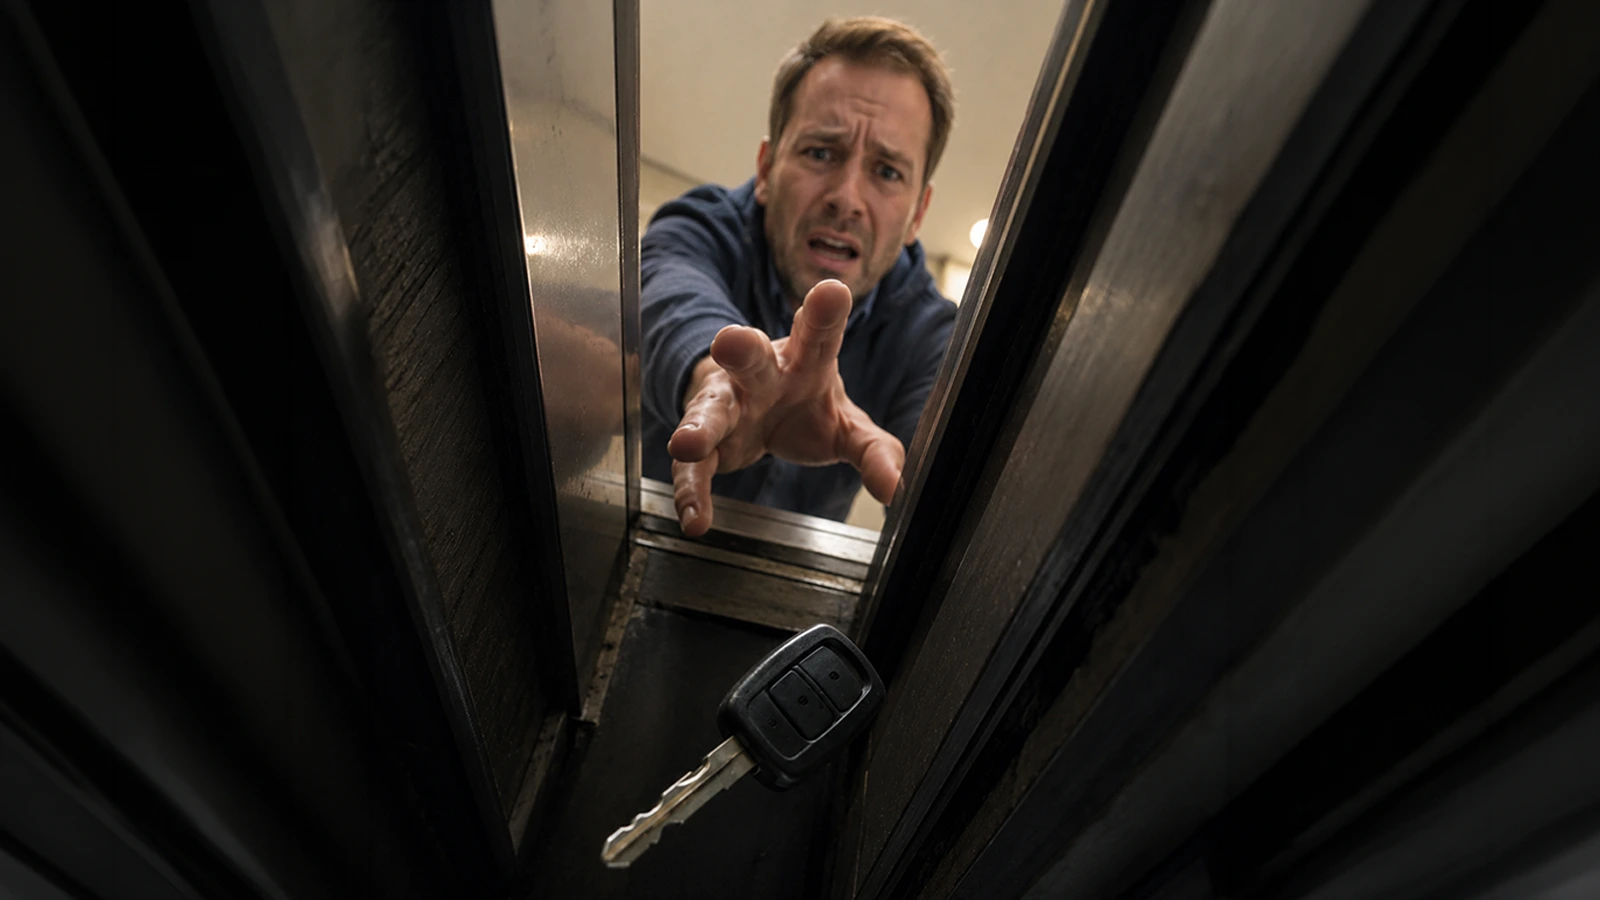 What does a tax compliance management system have to do with a lost car key?
There are those moments when you think to yourself: ‘That can’t possibly happen.’ And then it does: you’re standing in front of the lift in the office block, the doors open, everything as usual. A quick step forwards, your car key loosely in your hand – and suddenly it slips from your fingers. A faint metallic clink. A brief pause. And then that glance downwards: the key is gone. Vanished. Into the gap between the lift and the floor, exactly three centimetres wide.
 Award-winning: hsp now bears the TOP 100 seal
This year, hsp Handels-Software-Partner GmbH has been awarded the most prestigious accolade for innovation among SMEs: the TOP 100 seal. The jury, chaired by Ranga Yogeshwar, recognised the outstanding importance that innovation has held at hsp since its foundation in 1991; both in the continuous development of the Opti.Tax taxonomy solution and in the company’s structures and its role as a reliable industry partner.

 German
 English